Cost of Living
Why the date a bill lands matters more than its size
A manageable bill on the wrong day is a missed payment; the same bill three days later is routine.

Both approaches to bill timing work. What differs is what they cost you, and the cost is what this sets out.
The difference in one place
- Most billers will change a payment date on request without charge.
- Failed payment fees and returned charges add cost to a shortfall that was purely timing.
- Clustering bills just after payday reduces the number of exposed days.
Timing failures cost more than the shortfall
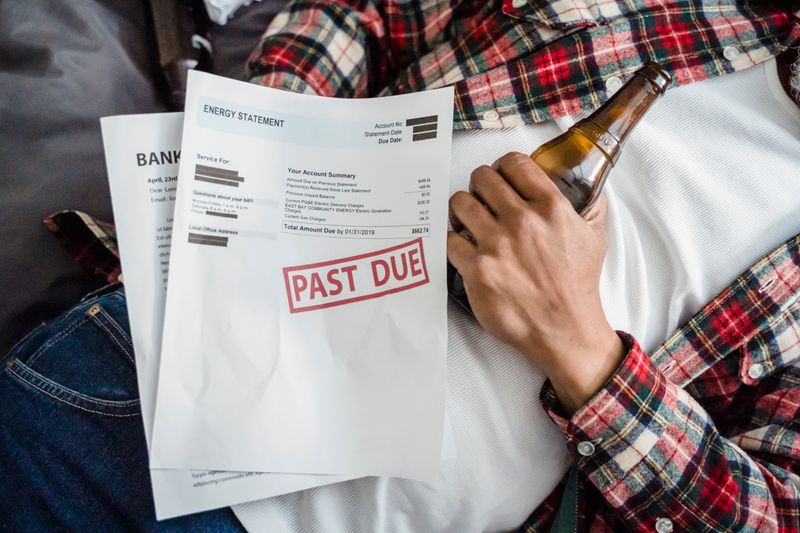
A payment that fails because it was attempted two days before payday can trigger a fee from the biller, a charge from the bank, and sometimes a knock-on failure of the next payment. The underlying shortfall may have been small and temporary; the added cost is not.
Repeated failures can also affect a lender's view of an account, which has consequences beyond the immediate charge. Almost all of this is avoidable by moving a date.
Dates are more moveable than people think
Utilities, telecoms, insurers, subscription services and many lenders will change a collection date on request, usually free and often within one cycle. It is an administrative call rather than a negotiation, and it does not require explaining your circumstances. Doing all of them in one session, listing each provider and the new date, takes an afternoon once.
The benefit repeats every month indefinitely.
Cluster just after money arrives
Setting collections for the days immediately following a reliable pay date minimises the number of days on which a balance must survive. Where income is variable, aligning to the earliest reliable point in the cycle rather than to an average is the safer version.
In practice, leave a gap of a working day or two after payday, since payment timing on weekends and holidays shifts. A single calendar of pay dates and bill dates is the whole exercise.
Weekends and holidays shift everything
Where a payday falls on a weekend or public holiday, some employers pay earlier and some later, and that varies within the same country. A collection set for the first of the month can therefore land before pay in some months and after it in others. Knowing your employer's rule removes the uncertainty.
The useful part is this: it is a one-line question to payroll.
Non-monthly cycles need mapping
Anyone paid four-weekly or weekly is aligning a non-monthly income to monthly collections, so no fixed date is safe every month. Mapping the whole year once identifies the specific months where a collection falls in a long gap. Those months are the ones to move, rather than trying to fix the system as a whole.
Put simply, the map is valid for a year and takes half an hour.
When it is not a timing problem
If bills exceed income regardless of when they arrive, moving dates changes nothing and the problem is the income or the costs. Free debt advice services exist in most countries and are the appropriate route rather than rearranging payments.
Providers also have hardship processes that are usually more generous than people expect and are rarely used early enough. This is general information rather than advice, and a regulated adviser or a free advice service is the right place for a specific situation.
Side by side
| Consideration | What it means in practice |
|---|---|
| Timing failures cost more than the shortfall | Most billers will change a payment date on request without charge. |
| Dates are more moveable than people think | Failed payment fees and returned charges add cost to a shortfall that was purely timing. |
| Cluster just after money arrives | Clustering bills just after payday reduces the number of exposed days. |
The takeaway
Move your bill dates to just after payday. It costs one afternoon and repeats every month.
Small and repeatable beats ambitious and abandoned, almost every time.
Questions readers ask
Can I change when a bill is collected?
Most providers will change a collection date on request, usually free and within a cycle. It is an administrative call, not a negotiation.
What if payday falls on a weekend?
Employers differ: some pay earlier, some later. Ask payroll for the rule, since it decides whether early-month collections are safe.
Also by Amine Belkacem
- The unpaid minutes at each end of a shiftHours & Conditions
- Rota notice, and the price of not knowing when you workHours & Conditions
- Travel time between jobs, sites and clientsHours & Conditions
- Paid in arrears: the month of work you are always owedCost of Living