Cost of Living
Why your own inflation is not the headline rate
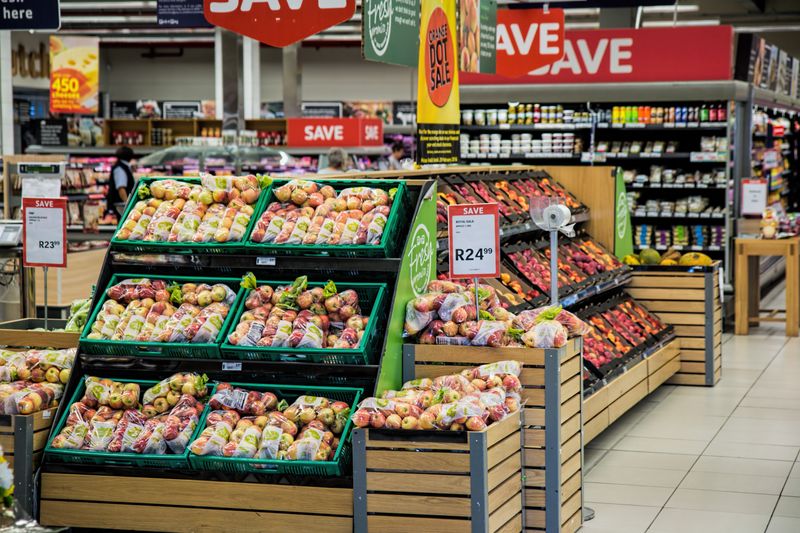
The published figure describes an average basket bought by an average household. Your basket is a different shape, and it usually moves faster.
Most explanations of personal inflation stop at the point where it starts to matter. This one carries on.
The short version
- Headline inflation is a weighted average across a representative basket.
- Lower-income households spend more of their money on essentials.
- A pay rise below your own inflation rate is a real cut.
How the headline figure is built
Statistical agencies track prices across a basket of goods and services, weighted by how much a representative household spends on each. The result is an average, and averages describe populations rather than the household reading about them. Someone who rents, drives and heats a poorly insulated home has a completely different exposure from someone who owns outright and works from home.
The basket is also updated periodically to reflect changing consumption, which means the comparison over long periods is not of identical items. None of this makes the figure wrong; it makes it the wrong tool for judging your own position.
Essentials weigh more when income is lower
Food, energy, housing and transport take up a much larger share of spending in lower-income households. When those categories rise faster than the average, the effective inflation rate experienced by those households exceeds the headline. Higher-income households hold more discretionary spending, which can be reduced or deferred when prices move.
That flexibility is itself a form of protection, and it is exactly what a household on a tight budget lacks. This is why a period of rising essential prices produces very different experiences that are all accurately described by one number.
Building your own figure
Take your last few months of spending and group it into the categories that dominate: housing, energy, food, transport and everything else. Note what each category cost a year ago, using bills and statements rather than memory. Weight the change in each by its share of your spending, which produces a personal rate that will often differ from the published one.
The useful part is this: it takes an hour and it changes what a pay offer means, since a rise below your own rate is a reduction in what you can buy. Repeat it annually rather than continuously, because the value is in the comparison rather than the precision.
Why prices feel worse than the figure
People notice frequently purchased items, so the price of a weekly shop registers far more strongly than an annual insurance premium. Inflation is a rate of change, so a falling rate still means prices are rising, just more slowly than before.
Prices that rose sharply do not usually return to previous levels when the rate falls, which is the source of most confusion about the figures. Quality and quantity changes at the same price are captured imperfectly and are experienced as price rises by shoppers.
Understanding the distinction between the level and the rate resolves most arguments about whether things are getting better.
What it means for pay
A pay rise matched to headline inflation preserves the average household's position rather than yours. Where your own exposure is higher, matching the headline is a real cut in what your wage buys.
Put simply, this is a legitimate and specific argument in a pay conversation, provided it is framed around the role and the market rather than personal need. The stronger version pairs it with evidence about what the role now pays elsewhere, since employers respond to market pressure more than to price indices. Over several years, small shortfalls against your own rate compound into a substantial reduction in living standards.
Adjust the size of it until it is something you would actually do tired.
Responses that actually work
The categories worth attacking are the large recurring ones, since a small percentage on housing or energy exceeds a large percentage on anything minor. Fixed costs renegotiated once keep paying back monthly, which is a better use of an hour than repeated small economies.
Substitution within essential categories helps, though it has limits and those limits arrive quickly on a tight budget. Beyond a point the only remaining lever is income, which is why prolonged price pressure eventually becomes a pay question. Being able to state your own rate, with workings, makes that conversation concrete rather than emotional.
The takeaway
Build your own rate once a year from your own bills; it is the only benchmark a pay offer should be judged against.
The version you keep doing is the version that works.
Questions readers ask
Why does inflation feel higher than the reported figure?
The figure is a weighted average across a representative basket. If housing, energy and food take a larger share of your spending, your own rate is usually higher.
If inflation falls, do prices fall?
No. A lower rate means prices are rising more slowly. Levels that have already risen generally stay risen, which is why a falling rate does not feel like relief.
Also by Marcia Delgado
- Reading a payslip properly, line by linePay & Payslips
- Zero-hours and variable contracts: what to check before signingRights at Work
- What a wage buys now compared with a decade agoCost of Living
- The costs of going to workCost of Living